Managing finances in the United States involves more than tracking income and expenses. Everyday decisions about saving, borrowing, spending, and investing can influence financial stability for years. A thoughtful approach helps people understand where their money goes and create priorities that match their circumstances, goals, and expectations.
Financial planning does not require complicated strategies or advanced knowledge. It begins with simple habits, realistic objectives, and regular reviews. By understanding cash flow, preparing for unexpected costs, managing debt, and making informed choices, individuals can build a stronger foundation while keeping their financial decisions aligned with long-term priorities.
Understanding the foundations of personal finances
Personal finances include the way money is earned, spent, saved, borrowed, and invested. Looking at these areas together makes it easier to understand financial health instead of focusing on a single number. Income provides resources, while expenses determine how much flexibility remains. Savings and investments can support future objectives, while debt creates obligations that must be managed carefully.
A useful starting point is to calculate monthly net income and compare it with recurring and variable expenses. Housing, utilities, transportation, groceries, insurance, subscriptions, and entertainment can all affect available cash. Reviewing these categories regularly can reveal spending patterns that are easy to overlook when purchases are made separately throughout the month.
Building a budget that reflects real life
A practical budget should describe how money is actually being used rather than relying on unrealistic assumptions. Fixed expenses can usually be estimated with reasonable accuracy, while variable categories require more flexibility. Creating separate amounts for essentials, discretionary spending, savings, and financial goals can provide a clearer structure for monthly decisions.
Budgeting also works better when it includes occasional expenses. Car maintenance, annual subscriptions, gifts, school costs, travel, and household repairs may not appear every month, but they still affect finances. Setting aside money gradually for these expenses can reduce pressure when they eventually arrive.
Creating stability through savings
Savings provide financial flexibility by creating resources that do not depend on new borrowing. An emergency fund can be particularly useful when unexpected expenses arise, such as repairs, temporary income disruptions, or urgent household needs. The appropriate amount depends on income stability, essential expenses, family circumstances, and other available resources.
Saving can become easier when it is treated as a regular financial commitment. Automatic transfers to a savings account can help separate money for future needs before it is spent elsewhere. Even modest contributions can establish consistency, and increasing them gradually may become more manageable as income or financial circumstances change.
Choosing suitable goals for different time horizons
Financial goals can be divided into short-, medium-, and long-term objectives. Short-term goals might include building savings for an upcoming expense, while medium-term goals could involve education, a vehicle, or a home. Long-term objectives may include retirement or building assets for future financial independence.
Each goal can require a different approach. Money needed soon generally benefits from accessibility and lower risk, while longer-term funds may have more time to tolerate fluctuations. Defining the purpose and timeframe before choosing where to keep money can help prevent decisions based solely on potential returns.
Managing debt with greater awareness
Debt can be useful when it supports an important objective and fits comfortably within a person’s financial capacity. However, interest charges and required payments can reduce future flexibility. Understanding the total cost of borrowing is therefore important before accepting a loan, using a credit card balance, or choosing another form of financing.
Comparing interest rates alone may not provide the complete picture. Fees, repayment periods, penalties, promotional conditions, and minimum payments can influence the actual cost. Reading the terms carefully and considering the total amount that will be repaid can help borrowers make more informed decisions.
Protecting credit while controlling borrowing
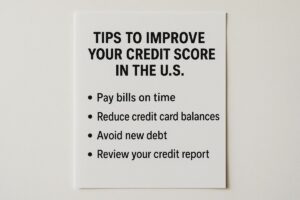
Credit history can influence access to financial products and the terms offered by lenders. Making payments on time, keeping track of balances, and reviewing credit reports can support responsible credit management. Borrowing less than the available limit can also provide additional flexibility when unexpected expenses appear.
People can also benefit from distinguishing between necessary borrowing and discretionary borrowing. Financing a major purchase may sometimes be reasonable, but repeatedly using credit for everyday expenses can create a cycle of payments and interest. A clear spending plan can help reduce reliance on borrowed money.
Making informed investment decisions
Investing can play an important role in long-term financial planning because money may have opportunities to grow over time. Common investment categories include stocks, bonds, mutual funds, exchange-traded funds, and other assets. Each option has different characteristics, including potential returns, risks, costs, and levels of diversification.
Before investing, it can be useful to identify the purpose of the money, the expected timeframe, and the amount of risk that can reasonably be accepted. Investing should not be approached as a guaranteed path to wealth. Market values can rise and fall, and past performance does not guarantee future results.
Diversification can help reduce dependence on the performance of a single investment or sector. Instead of concentrating money in one asset, investors may consider spreading exposure across different investments. The appropriate mix depends on individual circumstances, objectives, timeframe, and tolerance for fluctuations.
Reviewing financial progress over time
Financial planning is not a one-time activity. Income, expenses, family responsibilities, goals, and economic circumstances can change, making periodic reviews valuable. Checking a budget, savings progress, debt balances, and investment allocation can reveal whether the current strategy still matches personal objectives.
A review does not necessarily require major changes. Sometimes the best decision is simply to continue a sustainable routine. In other situations, a change in income or expenses may justify adjusting savings contributions, reducing discretionary spending, refinancing eligible debt, or reconsidering investment choices.
Financial resilience also involves protecting progress. Adequate insurance, organized financial records, appropriate emergency savings, and careful account security can reduce the impact of unexpected events. Keeping beneficiaries and important financial information updated may also be relevant to broader financial planning.
Ultimately, healthy finances are built through repeated decisions rather than a single perfect strategy. A person who understands their cash flow, maintains appropriate savings, manages debt carefully, and invests according to clear objectives can develop greater financial confidence. The goal is not to eliminate every financial challenge, but to create enough structure and flexibility to respond to them.